I approached SoLo Funds: Lend & Borrow as a practical finance app rather than a conventional borrowing service. Its central idea is simple: people can request short-term help from other members, while those with available money can choose to lend. That makes the experience feel more personal and community-driven than opening a standard credit product, but it also means the app deserves a more careful look than its friendly premise might suggest.
My overall view is positive, with an important condition: SoLo Funds is most useful when you treat it as a tool for handling a specific cash-flow gap, not as a permanent replacement for income, savings, or a traditional bank. I like the directness of the model and the way it gives users an active choice between borrowing and lending. At the same time, anyone considering it should understand that flexibility does not remove financial responsibility. The app can make an urgent situation easier to manage, but it cannot make an unaffordable repayment disappear.
How the community borrowing model feels in everyday use
SoLo Funds is a finance app developed by Solo Funds, and it is free to download. The service is aimed at adults who want a different route for short-term money needs or who would rather put some spare funds to work by lending. Its store summary, “Borrow On Your Own Terms. Lend to reap the benefits,” captures the two-sided design, although the real experience is more nuanced than that sentence suggests.
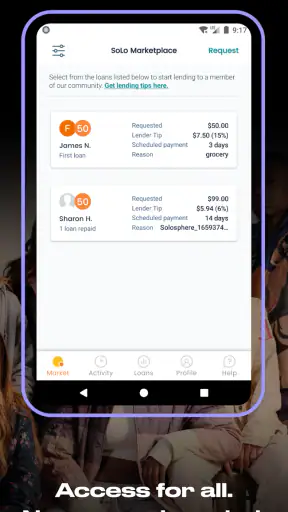
When I think about the app’s strongest quality, it is the sense of control over the purpose of the transaction. A borrower is not simply browsing a list of impersonal credit offers. The idea is to make a request within a member-based lending environment, while a lender can decide whether a particular request fits their comfort level. That structure may appeal to someone who dislikes the rigid, one-size-fits-all feeling of conventional financial products.
A realistic example would be a user whose paycheck arrives shortly after an essential bill is due. Rather than putting the expense on a high-cost card or allowing an account to fall behind, that person might use SoLo Funds to seek a short-term amount and plan repayment around the next income date. The important word is “plan.” The app is only helpful in this situation if the incoming money is dependable and the repayment amount has already been considered alongside rent, food, transport, and other commitments.
For a lender, the appeal is different. Instead of leaving every spare dollar idle, a user can review opportunities to support another member. That can feel more meaningful than using an anonymous financial product because the transaction has a visible human purpose. Still, I would not approach the lending side as effortless income. The decision requires judgment, patience, and a willingness to accept that lending involves uncertainty.
The app’s popularity gives it a substantial user base: it has passed 500,000 installs, with an average rating of 4.6 from roughly twenty-five thousand ratings. Those figures suggest that many people find the concept useful, but they should not be read as a guarantee that every borrowing request will work smoothly or that every user will have the same experience. A community marketplace depends on participation, timing, and individual circumstances.
The most useful habit is planning before opening the app
My first practical recommendation is to decide the exact amount and repayment date before making a request. It is tempting to start with the maximum amount that seems available, especially when an unexpected expense is pressing. A better approach is to calculate the smallest amount that solves the immediate problem. That reduces the repayment burden and makes it easier to judge whether the request is genuinely manageable.
This is also where SoLo Funds differs from a standard budgeting app. A budgeting tool helps you organize money you already have or expect to receive. SoLo Funds can help bridge a gap, but it does not replace the budgeting step. I would use a notes app or a simple calculator first, write down the expected repayment date, and check what remains after essential expenses. That small piece of preparation can matter more than the convenience of submitting a request quickly.
Another useful workflow is to separate urgent needs from recurring shortages. If the same bill creates a problem every pay cycle, borrowing through the app may only move the pressure forward. In that case, a conversation with the bill provider, a revised budget, a savings plan, or a conventional financial adviser may be more appropriate. SoLo Funds makes more sense for an isolated timing problem than for a structural gap between income and expenses.
Why the lending side needs a different mindset
Borrowers and lenders should not judge the app by the same standard. A borrower is primarily asking whether the process can provide timely assistance and whether the repayment fits their finances. A lender is weighing potential benefit against the possibility that a request may not unfold as expected. The community element is attractive, but it should not encourage emotional decisions.
If I were lending, I would treat each opportunity as money that might be unavailable for a while. I would not use funds reserved for rent, emergency expenses, debt payments, or near-term purchases. I would also avoid assuming that a positive story automatically means a safe lending decision. The human context can help explain a request, but it cannot replace careful limits.
That is one of the app’s less obvious trade-offs. The personal nature of the marketplace can make it feel warmer than a bank, yet warmth can also make users less analytical. A disciplined lender should set a personal maximum, keep lending money separate from everyday spending, and consider whether the possible return is worth the inconvenience of delayed access. Those safeguards are not flashy features, but they are essential to using the app responsibly.
Where the app compares well with familiar alternatives
Compared with a credit card, SoLo Funds may feel less like an open-ended spending facility. A card can be convenient, but it can also encourage a balance to remain in place while interest and fees accumulate according to the account terms. SoLo Funds is better suited to a defined, short-lived need where the user knows how the money will be repaid.
Compared with a payday lender, the community model may feel less transactional and more transparent in spirit. However, I would still read every screen carefully and make sure I understand the total obligation before accepting anything. A friendlier interface does not automatically mean a cheaper or safer outcome. The right comparison is always the actual repayment cost, timing, and consequences, not just the tone of the app.
Compared with asking family or friends, SoLo Funds offers a more structured way to make a request without placing the entire conversation inside a personal relationship. That can protect dignity and reduce awkwardness. The downside is that a digital process can feel deceptively easy; users may be less likely to pause and discuss whether borrowing is the best answer.
Compared with a savings account, the app serves an entirely different purpose. Savings provide control and predictability, while borrowing solves a present shortage by creating a future obligation. If someone has enough time to prepare, building even a small emergency reserve is usually the stronger long-term solution. I see SoLo Funds as a bridge, not a foundation.
The friction I would not ignore
The biggest limitation is that the app cannot guarantee that a borrower’s request will fit every situation or that a lender will always find an opportunity worth taking. A marketplace depends on other participants. If timing is critical, that dependence can be stressful. Someone facing a deadline should not assume that opening the app guarantees immediate relief.
There is also a psychological friction that is easy to overlook. Borrowing from a community can feel less intimidating than dealing with a bank, but repayment still requires the same discipline. The conversational, human-centered concept may reduce the emotional barrier to asking for help, which is valuable, yet it can also make borrowing seem more casual than it really is.
I would also be cautious about using it repeatedly. Even if each individual request seems small, a pattern of rolling short-term borrowing can make future income feel permanently committed. The app is not the right answer for someone who needs regular help covering ordinary living costs. That person may need a broader review of expenses, income, debt, or available public and nonprofit support.
Another consideration is trust. Any finance app requires users to pay attention to account security, identity details, repayment information, and the precise terms shown during the process. I would never rush through setup or accept an arrangement without reading the final figures. The free download does not mean every financial action inside the service is cost-free, so the screen-level details matter.
Who will get the most value from it?
SoLo Funds is a strong fit for someone with a temporary, clearly defined cash-flow problem and a realistic plan for repayment. It may also suit a financially organized lender who understands that community lending is not the same as a guaranteed savings return. In both cases, the user needs enough stability to make decisions calmly rather than reacting to pressure.
I can also see value for people who dislike conventional credit products but still want a formal digital process. The app creates distance from the discomfort of asking someone close for money while preserving a sense that the transaction involves real people rather than an anonymous institution.
It is a weaker fit for anyone with unpredictable income, several overdue obligations, or no clear repayment source. I would also steer away from it if the intended use is discretionary shopping, repeated bill coverage, or paying one loan with another. In those cases, the convenience could hide a deeper problem instead of solving it.
Lenders should skip the app if they need guaranteed access to their money or cannot tolerate uncertainty. This is not where I would place emergency cash. I would only consider lending money that sits outside my essential budget and that I could leave untouched without creating another problem.
Details worth knowing before installing
The app is listed for everyone in terms of content rating, and it runs on Android starting with version 8.0 or later. Its current version is 2.19.0, so Android users with older devices should check compatibility before spending time on setup. The service is also available as a mobile product rather than something I would approach as a traditional branch-based financial service, which makes phone access central to the experience.
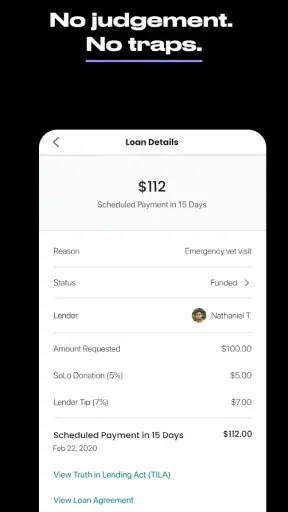
Because it is free, trying the app does not require an upfront purchase. That lowers the barrier for people who want to understand the workflow before deciding whether to borrow or lend. Even so, I would distinguish between the cost of installing an app and the financial terms of using its service. Before confirming any transaction, I would review the amount received, the amount expected back, the dates involved, and any applicable charges or optional contributions displayed in the process.
The app was released on October 22, 2021, and its continued presence in the finance category shows that the concept has had time to attract a meaningful audience. I would still keep the application updated and use the latest available version because finance tools handle sensitive activity and may change their screens or processes over time.
My final assessment
SoLo Funds stands out because it treats short-term borrowing and lending as a two-sided community activity rather than presenting only a conventional credit application. I appreciate that distinction. It can be a useful option when the need is temporary, the amount is controlled, and repayment is tied to a dependable source of money. The lending side can also appeal to users who want to make thoughtful, limited decisions with spare funds.
My reservation is equally clear: the app’s ease and approachable design should not be mistaken for financial safety in every circumstance. A marketplace cannot remove uncertainty, and a short-term solution becomes risky when it turns into a repeated habit. The best way to use it is deliberately—calculate first, borrow only what solves the immediate problem, and protect essential money if considering lending.
My recommendation is conditional but genuine: I would suggest SoLo Funds to financially organized users who need a defined bridge or who understand the risks of community lending. I would not recommend it as a substitute for emergency savings, stable income, debt counseling, or a long-term spending plan. Used with those boundaries, it offers a distinctive alternative in finance; used without them, its convenience may simply postpone the problem.


